

The most expensive page on a website is usually the one nobody wants to build: the payment form. It has one job, and it loses more sales than any other step. Baymard Institute puts the average cart abandonment rate at just over 70%, and 18% of U.S. online shoppers have abandoned an order because checkout was too long or complicated.
Software companies and businesses that build their own websites know the other side of that problem. “Add checkout” looks like a single line on the roadmap. In practice, it requires card field validation, error handling, mobile layouts, bank payment flows, industry compliance, and a security questionnaire nobody on the team has ever seen.
There’s a way to skip that build entirely and still give customers a smooth, secure way to pay. Let’s take a look at what a hosted payment page is, how it works behind the scenes, and why so many teams are handing checkout off to their provider.
What is a hosted payment page?
A hosted payment page is a checkout page that lives on your payment provider’s servers instead of your own website. When a customer is ready to pay, your site or software redirects them to that page. The provider collects their card or bank details, processes the transaction, and sends the customer right back to your site. Your systems never touch payment data.
The concept goes by several names, like hosted checkout, redirect checkout, or hosted payment gateway. In short, the provider hosts, secures, maintains, and updates the page for as long as you use it, so your team can focus on growing the business.
What are the benefits of a hosted payment page?
Handing checkout to a provider changes more than who writes the code. The provider takes on the security, maintenance, and compliance work that comes with touching payment data, and your customers get a payment experience built by an experienced team.
Here’s what that looks like in practice:
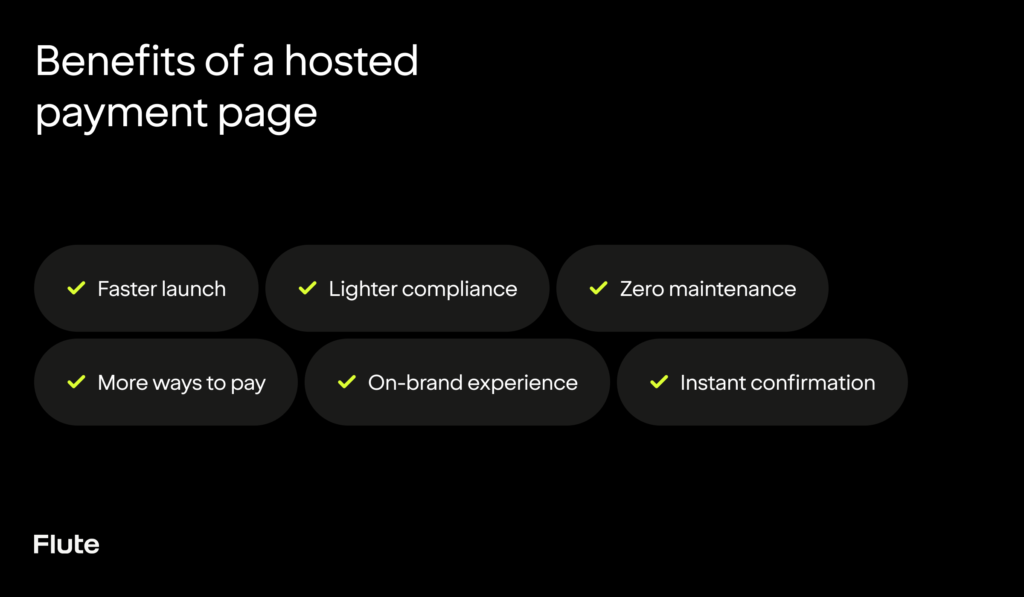
- Faster launch: connecting to a hosted page takes days, while building a checkout from scratch can take months
- Lighter compliance: customers enter their payment details on the provider’s servers, so sensitive data never touches your systems
- Zero maintenance: the provider keeps the page current as payment types, rules, and regulations change
- More ways to pay: card and ACH (bank-to-bank) payments live on the same page, so customers have more options
- On-brand experience: your logo and colors stay the same, so you don’t have to worry about customers being sent to an unfamiliar page
- Instant confirmation: your system hears back the moment a payment succeeds or fails, and orders update on their own
How does a hosted payment page work?
After integration, the model relies on what’s called a payment session. Here’s how it works, from click to confirmation:
- Session creation: your backend makes an API call to the provider with the transaction details, including the amount, the currency, which payment methods to offer, and a reference like an order ID
- URL returned: the provider responds with a unique, one-time URL for that checkout session. The link expires after a set window. Because the amount was set when the session was generated, it can’t be tampered with or reused
- Redirect: your software redirects the customer to that URL. When done well, the handoff is barely noticeable, since the page can be customized with your branding and logos
- Payment collection: the hosted page populates the payment form, with card fields, an ACH payment option, and a mobile-friendly layout, and handles validation, error states, and accessibility
- Return and confirmation: the customer lands back on a success or failure page (that you’ve specified when creating the payment session), and the provider notifies your system of the result so you can mark the order paid and kick off fulfillment
That’s the whole integration: one API call out, one notification back. Everything between those two moments is the provider’s job.
Why businesses hand checkout off to their providers
There are three main reasons why businesses prefer to let their payment providers handle checkout: the challenges of building a checkout page in-house, meeting industry compliance, and maintaining customer trust.
1. Building the checkout
A payment form is deceptively hard to get right. Card numbers need to be formatted and validated as the customer types; errors need clear recovery paths; the layout has to work on a five-year-old phone; and bank payments follow different rules than cards do.
The work never ends, either, because card networks and regulations keep changing. A hosted page eliminates the need to worry about any of that.
2. Meeting compliance
Any business that accepts card payments falls under the Payment Card Industry Data Security Standard (PCI DSS) and must meet a strict set of regulations. The burden scales with the volume of card data your systems handle, so the more you sell, the harder it is to stay compliant.
With a hosted page, customers enter card data directly on the provider’s servers, which means your systems never see it. That puts you at the lowest compliance level and turns what could be a months-long audit into a manageable project.
3. Maintaining trust
In a recent report on why shoppers abandon purchases, 19% said they didn’t trust the site with their credit card information. A hosted page helps because customers aren’t typing their card number into a small business’s website — they’re entering it on a page built and secured by a payments company, one that screens for fraud and is designed to protect card data. Customers can feel the difference, even when they can’t name it.
The customization trade-off
Hosted pages do ask for something in return: your customer briefly leaves your site to pay, and you don’t get to design every detail of the page they land on. Providers have closed most of that gap by letting you add your own logo and colors, so the handoff barely registers. Still, some large companies with large engineering teams choose to build their own checkout via a direct payment gateway integration, simply because they want to own every step themselves.
For most growing businesses, that trade is worthwhile. You give up a little design control and get back the months of building, the ongoing upkeep, and most of the compliance work that comes with handling card data.
Who gets the most from a hosted checkout page?
A 2025 McKinsey merchant survey found that roughly 90% of U.S. merchants use an integrated software solution for payments or business management, up from 48% in 2022. If your customer is already on your website or in your app when it’s time to pay, a hosted page picks up right where they left off and completes the sale.
Say an independent contractor wraps up a week-long home renovation and the customer asks how to pay. Mailing an invoice means waiting a week or more, and it might get lost along the way. Texting a secure checkout link lets the customer pay on the spot, by card or bank transfer, before the truck leaves the driveway.
Contractors are just one example. The same handoff works across most industries:
- SaaS platforms and vertical software: booking, point of sale, and field service platforms that embed payments into their products without building payment screens
- Retail and e-commerce: online sellers that want customers to move from storefront to payment without any checkout code to maintain
- Home services and trades: contractors, cleaners, and landscapers collecting payment after the job is done, on any device
- Health, wellness, and fitness: studios, salons, and practitioners charging for sessions, memberships, and packages
- Food, hospitality, and events: restaurants, caterers, and venues collecting deposits, pre-orders, and event payments online
Getting started
Checkout is the moment your customer decides to trust you with their money, and it deserves more than a rushed build. A hosted payment page lets you meet customers in that digital moment with an online checkout that’s secure, accessible, and always up to date, without pulling your team off the product.
That’s exactly what we built our hosted checkout experience to accomplish. One API call creates a payment session and returns a hosted, branded checkout URL where customers pay by card or ACH on a mobile-ready page that meets Web Content Accessibility Guidelines (WCAG) standards.
Your existing pricing settings, like surcharging, cash discounting, and dual pricing, apply automatically. Partners typically go from first API call to live checkout in days.
If you’re ready to stop building payment forms and start taking payments, reach out to our team to see how a hosted checkout page would work for your business.
Payments used to be a box for software companies to check: pick a processor, integrate, and move on. But that mindset is fading fast. Today, vertical SaaS (software as a service) platforms are treating payments — and the financial products that follow — as a genuine line of business, one that drives new revenue, deepens customer relationships, and makes their software more valuable to users.
But knowing the opportunity exists and actually capturing it are two different things.
How does a software company decide which embedded finance model fits? What makes customers actually adopt a payment product? And where does the opportunity go after payments?
To answer those questions, I sat down with Greg Myers, host of the Leaders in Payments podcast, to talk about how software companies can turn payments into a successful business.
Read a highlight of our conversation below, or listen to the full podcast.
What embedded finance means for vertical SaaS
Greg Myers: Vertical software companies are starting to look beyond their core platforms to explore how payments and other financial products can create new revenue, strengthen customer relationships, and deliver a smoother experience.
When you hear the term “embedded finance” today, what does it mean to you, specifically from the perspective of vertical SaaS companies?
John Badovinac: Embedded finance is the next evolution of the questions being asked by really smart developers.
What I mean by that is, many of the SaaS partners I speak with grew up in the specific vertical they serve. At some point, they started asking questions about that business — not just their payment-related needs — but the overall needs of that business. And the better those questions were, the better they could develop a product to meet those needs more comprehensively.
And so, the next evolution beyond payments is broader embedded finance. That means that once we’ve established payments and understand a platform’s typical spend and transaction volume, we can identify additional financial services like working capital and embed them in a way that fits naturally within the software merchants already use every day.
Myers: Payments, as you know, have been historically viewed by software companies as an integration or a feature. Today, that’s changing. So, why do you think that more vertical SaaS companies are starting to view payments as an actual line of business?
Badovinac: I think it’s primarily because they want to own more of the experiences that are important to them. When they think more deeply about how they differentiate themselves and the solutions they provide for their users, they have to own more of the overall experience to set themselves apart from competitors.
At Flute, we help them think through not just connecting features and executing an integration, but how to build a payment business.
That starts with a consultancy that models different pricing options and helps them build an authentic in-app experience that makes it really easy for their customers to participate. We also help them understand how to incorporate payments into the right place within their user journey.
Every integration differs by vertical. Some SaaS customers need scheduling and in-app payments, while others need invoicing, text to pay, or contactless options like Apple Pay. So instead of just embedding a checklist of payment features, we help identify the right payment feature for their use cases and thoughtfully surface it at the right time within their native UI.
How to know when a platform is ready to own payments
Myers: When you sit down with these vertical SaaS companies, what tells you whether they’re truly ready to own more of the payment experience?
Badovinac: The key thing I look for when I talk to a software provider for the first time is their value proposition. What’s their unique right to win? What is going to deliver the value they’re solving within the problem sets they’ve identified?
Secondly, do they have a sales playbook that really works? Or are they relying on their founders and their personalities to drive sales?
Finally, is their operations playbook up to snuff? I always ask about their CRM (customer relationship management) tools and how they’ll support everything once payments are embedded.
Those are prerequisites to knowing they’re ready to scale. When a platform has those three things — a repeatable sales playbook, a tight CRM, and a solid support structure — then we can pair that with a unique value proposition and really start to dig in.
Myers: There are several different models a software company can use to embed payments and other financial services. There’s the simple referral model, the PayFac (payment facilitator) model, and a fully integrated approach. In your opinion, how should a SaaS company think through which model is right for them?
Badovinac: That’s a great question. I would start by asking what experience they want to deliver to their customers, and how that applies to their overall value proposition. I always recommend that they own whatever is most important to them and then find a partner or outsource the rest.
So, if they need to be set up fast, then onboarding with minimal friction and as few questions as possible is most important. But if they want a more personalized journey that’s not as time-sensitive, they can onboard at a more leisurely pace and explore more advanced features.
Whatever sets a SaaS company apart, and what differentiates them the most, will ultimately drive what they need to fully own and optimize versus what can be outsourced to someone else.
What drives real payment adoption
Myers: A software company can build a great payments product, but that doesn’t necessarily mean that their customers are going to use it. So what are the companies achieving strong payment adoption doing differently?
Badovinac: I think the best answer to that is to make the payment experience natural and genuine within the platform’s workflows.
I’ll give you an example: I spoke with one platform that made it possible for a medical practitioner to look at their schedule of completed appointments and then send bills, like text reminders or digital payment links, directly from their calendar.
That’s a nice way to align functional software features with a collections- or payment-related opportunity. It’s about working payments into the most contextually appropriate setting and then making it easy for that customer to use.
Embedded finance opportunities beyond payments
Myers: We’ve been talking about payments, but there are opportunities for other financial products like working capital, lending, payroll, accounting, and banking products. In your opinion, what’s the next phase for embedded finance beyond payments?
Badovinac: That opportunity starts with payments, where platforms can start to generate data and create workflows that are easy for their users to engage with. From there, working capital and instant payouts are natural extensions, since they rely on the data generated from payments.
From there, the next frontier is asking the right questions about the next phase of that business need: How can I access my funds faster, and how can I control where they’re used? To me, that means card issuance with spend controls. Working capital and instant payouts can be deployed directly to company expense cards that can only be used where intended, up to defined limits, with enhanced reporting and reconciliation
So, thoughtful applications of technology and rules-based governance could go alongside issued cards as a logical next step.
Building a payments business, not just an integration
Myers: You’ve been working with software companies for a long time. What are some of the biggest mistakes you still see companies making when they’re starting to embed payments?
Badovinac: The first was assuming that because our partners were software experts, they’d also be payments experts. Payments pricing and statement analysis can get complicated quickly, and I learned that we needed to provide more guidance rather than asking partners to make all of those decisions on their own.
Now, we consult with them upfront on profitability levers and go-to-market pricing, build pricing templates directly into automated enrollment, and even assign a relationship manager who can take applications, train their team, and help them gradually own more of the onboarding experience.
The second mistake I see is thinking that integration is the end of the journey. It’s not — it’s just the starting point.
The most important thing is whether they have natural adoption and whether they’re getting traction from the payment interfaces they’ve embedded into their native SaaS UI. If they’re not, then they need to tweak something. So, some education needs to happen as well.
To me, the ultimate measure of success is when they start to gain traction on their own without a lot of effort from their end customers.
Myers: When a vertical SaaS company is evaluating embedded payment partners, what is it about Flute’s approach or capabilities that truly makes you unique?
Badovinac: That’s a great question. First and foremost, we can get SaaS platforms live in days. We use agentic development to dramatically reduce the time, cost, and engineering effort required to integrate, which lowers the risk and expense of getting started.
Another benefit is the consultancy we provide. We help them build a pricing policy that makes sense, then embed it into templates within their UI using an onboarding API — and integrate webhooks natively so onboarding and enrollment data flow into their UI in real time.
We also have a dedicated engineering team, which means we’re uniquely equipped to collaborate and build out additional functionality based on the frontline demands and insights our customers have.
Myers: What’s one thing you want vertical SaaS leaders to understand about building a payments business inside their software?
Badovinac: The biggest thing I’d tell them is that you’re not just integrating payments — you’re building a payments business. The integration is actually the easy part. You have to think about the economics, where payments belong in the user journey, how you’re going to drive adoption, and how you’ll support it as you scale. The right partner should help you with all of that, not just hand you APIs.
Listen to the full conversation here.
To see how Flute could work for your software platform, visit our developer site here and click “Build with AI” to get started.
For most U.S. businesses, credit card sales take one to three business days to land in the bank. If you’ve ever wondered why it takes that long, or whether you really have to wait to access money you’ve already earned, the answer comes down to one process: settlement. Once you understand how settlement works, it’s much easier to plan your cash flow around it.
So, let’s take a look at what happens between the tap and the deposit, why the system moves at the pace it does, and what you can do when you need faster access to your earnings.
What is credit card settlement?
When a card is approved at checkout, that money has to go through a series of approvals before it can be transferred to you. Settlement is the process that moves money from your customer’s card-issuing bank to your business bank account.
First, the customer’s bank has to confirm the funds exist and set them aside. Timing varies by processor, industry, and batch schedule, but the standard window in the U.S. is one to three business days. Some processors offer next-day funding, while others hold funds longer for newer merchants or higher-risk industries.
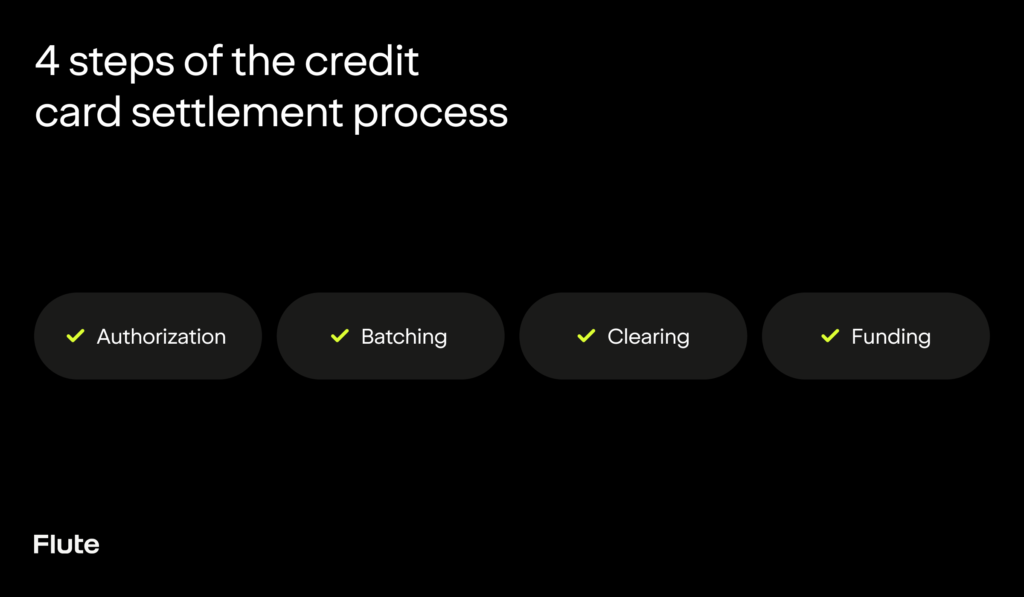
This process can be broken down into four key steps:
- Authorization
- Batching
- Clearing
- Funding
1. Authorization
This is the moment of purchase. Your terminal or checkout page sends the card details to your payment processor, which routes them through the card network to the customer’s bank.
That bank confirms the funds are available and runs its fraud checks, then sends back an approval within a second or two. The funds are now earmarked for you — but they’re still sitting in the customer’s account.
2. Batching
Approved transactions collect throughout the day in a queue called a batch. At a set cutoff time, usually in the evening, your processor closes the batch and submits every sale at once. This is why timing matters; a sale that lands after the cutoff has to wait for the next day’s batch, which can add a full day to its journey.
3. Clearing
Once the batch is submitted, the card network routes every transaction to the bank that issued each customer’s card. Those banks release the funds, calculate processing fees, and move the money to your processor’s bank. This step is where most of the waiting happens, since transfers run on systems that operate only on business days.
4. Funding
Finally, your processor deposits the settled funds into your business bank account. This is the only stage you actually see: the deposit that arrives one to three business days after the sale.
Why settlement takes a few days
If a card can be approved in two seconds, why does the money take days to arrive? Because the settlement system was built to prioritize accuracy and security over speed.
There are a few forces at work during this process:
- Multiple institutions have to agree: Your processor, the card network, the customer’s bank, and your bank all verify and reconcile each transaction before funds are released
- Fraud and risk checks take time: Banks screen transactions for fraud and potential chargebacks, which protects you as much as it protects your customers
- Batches run on schedules: Transactions move in daily groups rather than one at a time, and each hand-off has its own processing window
- Banks keep business hours: Traditional settlement rails don’t run on weekends or federal holidays, which is why Friday sales often arrive the following Tuesday or Wednesday
Each step is quick on its own. Stacked together, and paused every weekend, they add up to the familiar multi-day wait.
What a few days of waiting means for your cash flow
For a business with deep reserves, a two-day delay won’t make much of a difference. Most small- and medium-sized businesses don’t have that luxury.
One analysis of nearly 600,000 small businesses found that the median business has only 27 days of cash buffer, with restaurants having just 16. When your margin for error is measured in days, the gap between earning money and receiving it matters.
The speed of incoming payments matters, too. A 2025 report found that 60% of small businesses with longer payment terms experience cash flow problems, compared to 40% of businesses that get paid immediately. That means the faster money comes in, the fewer hard choices you have to make down the line.
Picture a caterer wrapping up the busiest weekend of the season. Although Saturday’s card sales were the best of the year, they need cash on hand Monday morning for their supplier. They also have to cover payroll on Tuesday. The revenue exists; the caterer earned it over the weekend, but those funds won’t reach their account until midweek — after bills and payroll are due.
That’s the settlement gap in real life: plenty of sales coming in, but a mismatch between when money is earned and when it arrives.
How instant payouts help you access revenue faster
You can’t skip the settlement process, but you also don’t have to wait on it. Instant payouts let you move card revenue you’ve already earned into your bank account within minutes, on demand, any day of the week — including weekends and holidays. Instead of following the traditional banking timeline, the funds travel over real-time payment rails that operate around the clock.
Faster money movement is well underway across the economy. Recent Federal Reserve surveys found that 86% of businesses used faster or instant payments in 2023. Another report projects that real-time transactions worldwide will more than double to 575.1 billion by 2028, with North America among the fastest-growing regions.
Growing businesses are desperate for faster access to revenue. One study found that 42% of small businesses would pay a fee to receive ad hoc payments instantly. And in our survey of 210 small-business operators, 37% said instant or same-day funding would help their business become more profitable or efficient.
Instant payouts usually carry a small per-transfer fee, around 1.75%, so many merchants stick to their usual settlement for everyday operations and reach for instant payouts when timing is tight, like a payroll run that can’t slip or a restock before a busy weekend. And because the money is revenue you’ve already earned, there’s nothing to apply for, no interest, and no debt on your books.
What this means for your business
Settlement isn’t going away; it’s the backbone of card acceptance and makes the industry more secure and reliable. The difference is that business owners no longer have to wait for typical settlement times to access their earnings.
If you’re already a Flute customer, your first instant payout is a few clicks away. Sign in to your dashboard, open the Finance section, and request your payout. The funds arrive in minutes.
Not a Flute customer yet? Reach out to our team, and we’ll show you how instant payouts can work for your business.
Payment friction is one of the few business costs that never shows up as a line item. It looks like a deposit that lands two days after payroll was due, an hour lost to reconciling statements, or a processing fee no one can quite explain.
The costs are real. They’re just easy to miss until you add them up.
In our latest report, “The Visibility Problem: What It Costs When Payments Won’t Get Out of the Way,” we surveyed 1,000 U.S. consumers and 210 small-business operators about how payments shape their buying decisions and their businesses. Our first look at the data focused on the checkout experience and what consumers want when they pay.
Now, we’re turning to the other side of the counter: how operators feel about their payment tools, and how those tools affect their time, cash flow, and ability to grow.
Most operators say their setup is fine. The data tells a more complicated story.
“Fine” is doing a lot of heavy lifting
Nearly 88% of the operators we surveyed said their payment tools fit their business well, and 51% reported no major challenges. On the surface, it sounds like everything is working. But that picture starts to change when you dig a little deeper:
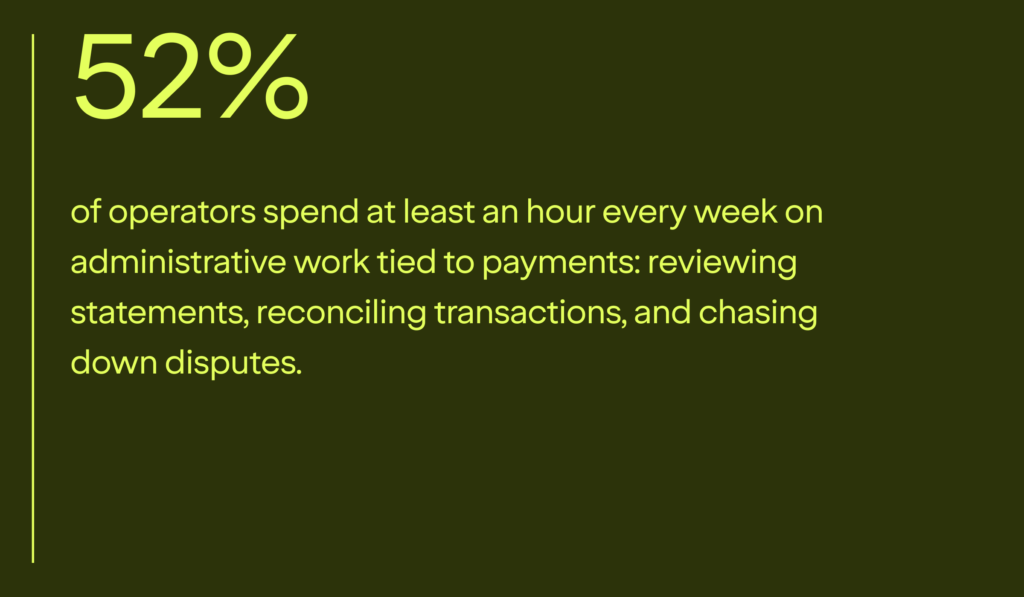
- 52% of operators spend at least an hour every week on administrative work tied to payments: reviewing statements, reconciling transactions, and chasing down disputes
- 38% of operators say their payment setup has definitely or probably cost them a sale
- More than one-third manage their finances across two or more separate systems, platforms, or logins
- 17% said that having everything in one system is the one thing they’d change about their payment experience
- 33% said better pricing or fee transparency was their top reason to switch processors
When card sales live in one dashboard, bank details in another, and accounting software in a third, payment reconciliation can become an unnecessary burden.
For small businesses, the work involved in checking for accuracy and making the numbers match doesn’t get handed to a back-office team; it falls to the person already managing customers, inventory, payroll, and growth. Across a full year, one hour of payment admin a week adds up to more than a full workweek of lost time.
When cash runs short, it gets personal
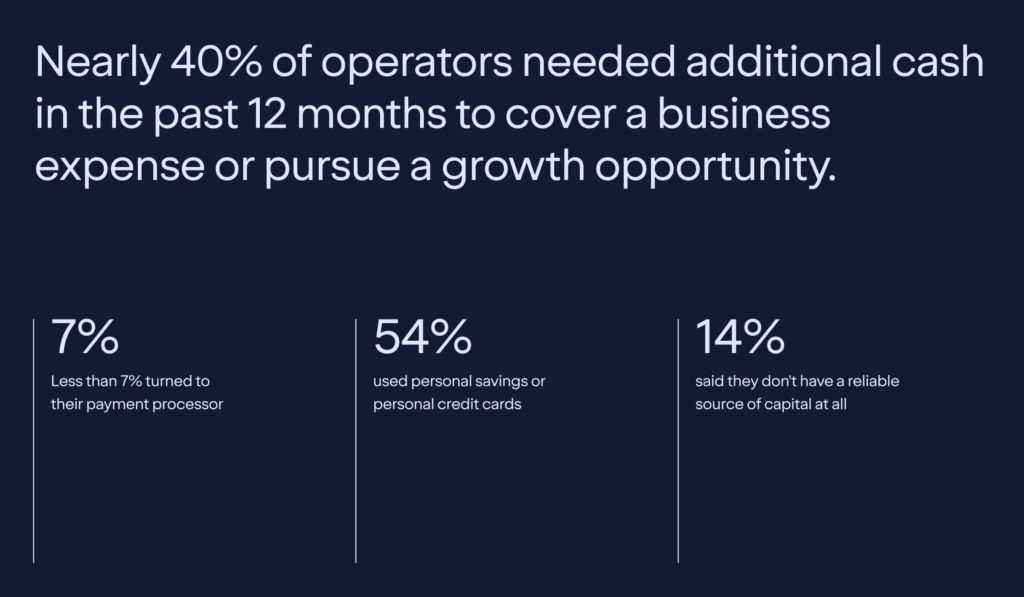
Slow funding creates cash flow problems that can feel impossible to work around. Nearly 40% of operators needed additional cash in the past 12 months to cover a business expense or pursue a growth opportunity. Another 36% said they’ve delayed a business expense like payroll, inventory, or rent in the past year while they waited on deposits to arrive.
The JPMorgan Chase Institute found that the median small business only has 27 buffer days in reserve — less than a month of operating cash. Another study found that nearly half of small businesses feel negative effects within one day of being unable to access their funds.
Consider a boutique that has its best sales day on Saturday. They have a supplier invoice due Monday, and payroll on Tuesday, but their weekend card sales won’t settle until midweek. The invoice won’t wait, and their employees need to be paid on time, so the boutique owner dips into their own savings to cover the difference. In this case, the money exists; the business just can’t access it yet.
Traditional financing isn’t filling the gap, either. In the Federal Reserve’s latest Small Business Credit Survey, only 42% of employer firms that applied for financing received the full amount they applied for, and 22% received nothing at all.
Where operators turn for funds when traditional avenues fall through says a lot about the state of small business funding:
- Less than 7% turned to their payment processor
- 54% used personal savings or personal credit cards
- 14% said they don’t have a reliable source of capital at all
When inventory or payroll goes on a personal credit card, the line between business and personal finances blurs, and the owner ends up carrying weight the business should be able to carry on its own.
The irony is that a payment processor can see a business’s revenue more clearly than almost any lender, yet when cash ran short, fewer than 1 in 14 operators turned to their payment provider for working capital. Until recently, most processors gave them no reason to.
Today, that dynamic is changing, making it easier for operators to access affordable financing and faster payouts through the platform they already use to manage payments.
What operators say would actually help
When we asked which capabilities would make their businesses more profitable or efficient, 37% pointed to same-day or instant payouts. The desire for faster access to earnings won out against everything else we tested, including better analytics, lending, and AI tools.
Pricing came through nearly as loud. Thirty-three percent said better pricing or fee transparency was their top reason to switch processors, ahead of features, hardware, and support. Operators are tired of dealing with hidden fees and confusing, inaccurate data, and are increasingly choosing flexible, transparent processors over outdated legacy providers.
Businesses aren’t asking for much here. They want to focus on growing their business without having to wonder where their money is going, how much they’re paying, or when their earnings will land in their account.
Your payment setup should carry its own weight
For consumers, payment speed is convenience. For operators, it’s control — over deposit timing, fees, time spent on payment admin, and funding.
If your current setup means weekly reconciliation marathons, days spent waiting for your own money, and cash gaps you have to cover out of pocket, you’re paying a tax that never appears on a statement. Growing businesses deserve better: transparent pricing, funding that moves when the business needs it, and one system for everything.
Download our full report, The Visibility Problem, to see everything the data revealed about payments, cash flow, and the everyday economy.
A limo driver finishes a corporate airport run, but their card reader won’t connect. An electrician completes a service call and needs to collect payment before heading to the next job. A fundraiser coordinator is setting up for an event and realizes they forgot their payment terminal.
Things like this happen all the time, which is exactly why tap to pay has become essential for so many businesses. It’s a technology that lets you accept payments from anywhere using just your smartphone. If you need more flexibility in how you take payments, tap to pay changes everything.
What Is Tap to Pay (and How Does It Work)?
Tap to pay is a type of mobile point of sale (mPOS) system. But unlike other mPOS systems that require a card reader or terminal, tap to pay uses your smartphone’s built-in Near Field Communication (NFC) technology.
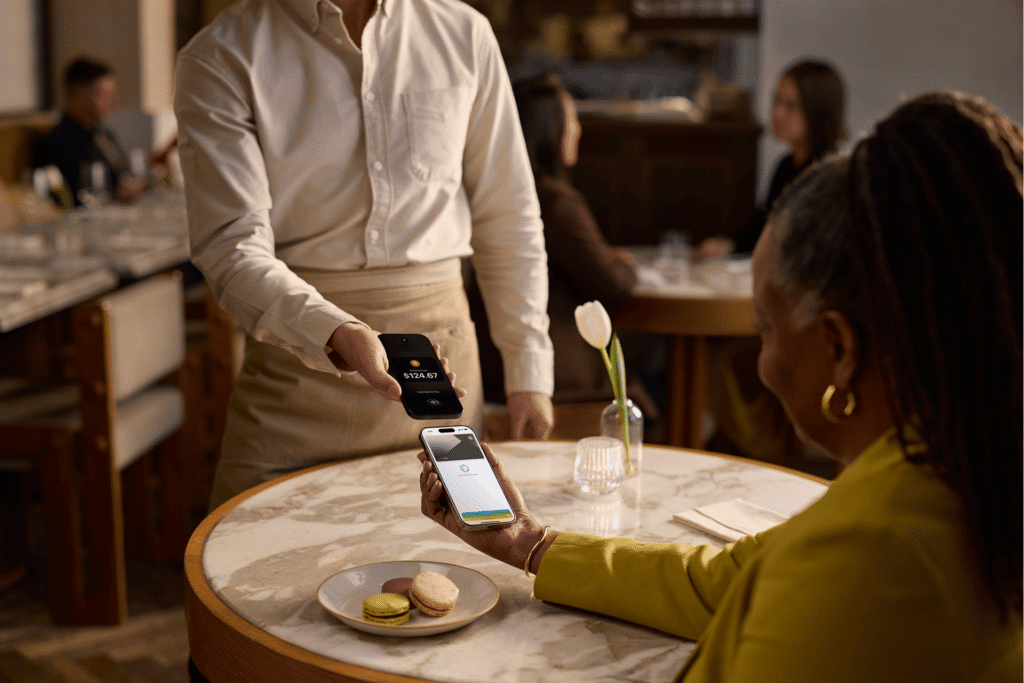
To accept a payment, you just need to download an app to your phone or tablet. When a customer is ready to pay, they just tap their phone, watch, or credit card to your device. There’s no separate hardware to purchase, charge, or carry around — everything happens on your smart device.
How Tap to Pay Compares to Traditional and mPOS Systems
If you’re evaluating payment options, it helps to understand the different choices and what trade-offs you’re making.
Traditional point of sale systems (the kind you see at most retail counters) offer robust features like advanced inventory management and integrated employee scheduling. But these capabilities come with a few challenges.
For instance, with traditional POS terminals:
- The upfront costs can be high
- They require regular maintenance and software updates
- Employees need training on how to use them
- They tie your team to a fixed location in your store
Using mPOS devices solves the mobility problem, but they still require separate hardware. You have to buy card readers, keep them charged, replace them when they break, etc. For small and medium-sized businesses operating on tight budgets, these costs add up quickly.
Tap to pay takes a different approach entirely. What it lacks in advanced functionality compared to full POS systems, it makes up for in price, speed, ease of use, and flexibility. Tap to pay’s advantage over mPOS tools is that there’s no hardware to purchase or maintain. All employees have to do is download the app on their phones, and they’re ready to go.
Is Tap to Pay Secure and Professional?
Something as easy to use as tap to pay can’t be as safe and secure as a traditional POS system, right? Wrong — and in some ways, it’s actually more secure than traditional card readers.
Every tap to pay transaction is fully Payment Card Industry (PCI) compliant, which means it meets the same strict security standards as any other payment processing method. But what makes it even more secure is that sensitive card data is never stored on your device. When a customer taps their card or phone, the transaction data is encrypted and sent directly to the payment processor. That means you never have to handle or store personal payment information, which reduces your liability and compliance burden.
How professional the experience is matters, too, and the mobile interfaces certainly deliver in this area. Apple’s Tap to Pay on iPhone, for instance, looks sleek and polished, with clear transaction confirmations and professional receipting options. For your customers (especially younger ones), offering tap to pay signals that you’re modern and tech-savvy, not that you’re lacking proper equipment.
6 Ways Tap to Pay Helps Businesses Grow
Beyond the obvious convenience of not having extra equipment to cart around, tap to pay offers six practical advantages that help you operate more efficiently and capture more revenue.
Accept payments anywhere
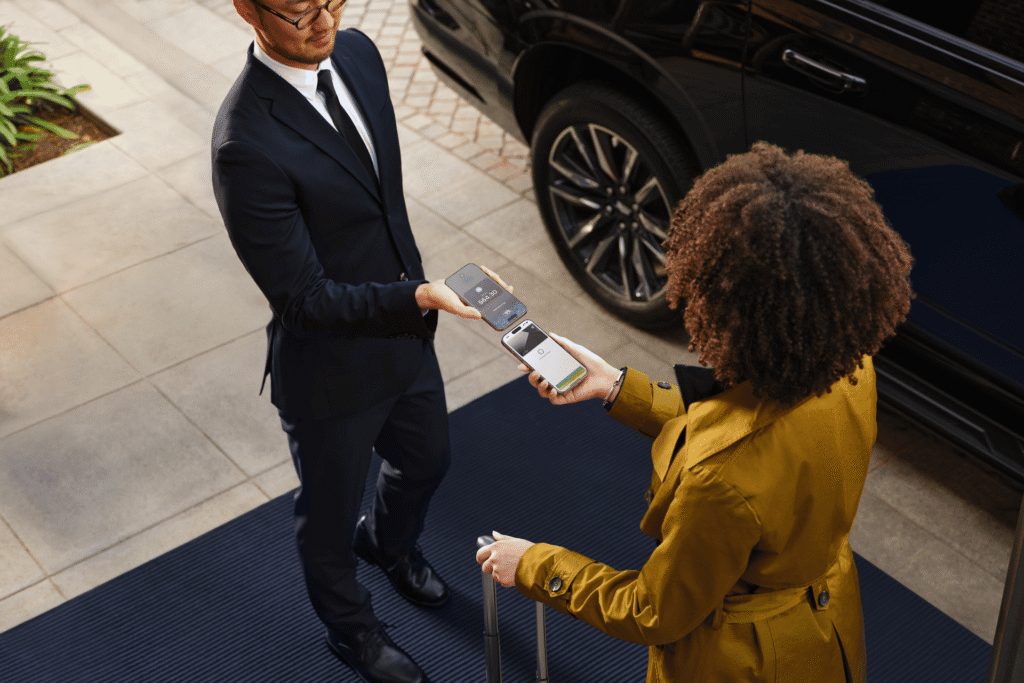
With tap to pay, all you need is your phone and cell service. This flexibility is great for those who operate on the go, like luxury transportation services, merchants who travel to craft fairs or pop-up shops, or consultants who provide on-site services.
Get up and running instantly
To get started, download the app and enable tap to pay on your iPhone. That’s it. For new businesses or those testing new sales channels, this removes a major barrier to entry.
Access lower fees
With tap to pay, you don’t have to budget for extra payment equipment and ongoing maintenance costs, or worry about upgrading your POS system over time. Everyone already has a phone, so why not take advantage of it?
Make it easier to get paid
You don’t need to buy a device for every employee, pass around a shared card reader, or wait for your one knowledgeable employee to check someone out. Anyone can collect a payment at any time.
Cater to your customers’ preferences
The convenience of tap to pay is now an expectation — more than 80% of Gen Z and Millennials prefer contactless digital payments and will look to competitors if you don’t offer them.
Get paid faster
With tap to pay, you can accept payment at the point of service, instead of sending an invoice when you get back to the office and waiting the typical 30 days to get paid. It’s not only more convenient for your customers, but it also eliminates the need to chase down payments.
Who Benefits Most From Tap to Pay?
While tap to pay can work for almost any business, those in certain industries see the biggest advantages. Here’s where tap to pay tends to have the most immediate impact.
- Retailers with seasonal spikes: If your retail business experiences high-traffic periods like holidays or special events, tap to pay lets you quickly add payment capacity without investing in more equipment
- Small and growing businesses: When every dollar counts, eliminating hardware costs and maintenance fees makes a real difference
- Luxury transportation operators: Drivers can take payments directly from passengers without bulky equipment taking up space in the vehicle
- Service professionals: Contractors, plumbers, electricians, and other service providers working on-site or in the field can collect payments immediately after completing work
- Businesses with small or rotating teams: When employees come and go, or you have seasonal staff, the ability to use personal devices (with your payment app) simplifies onboarding
- Organizations running events, markets, or fundraisers: Temporary setups benefit from payment solutions that don’t require bulky infrastructure or advance planning
The common thread across these businesses is the need for flexibility without sacrificing professionalism or security. If your business deals with any of these situations — unpredictable locations, tight margins, seasonal fluctuations, or teams that work outside a traditional storefront — tap to pay often makes the most sense.
Making the Switch to Mobile Tap to Pay
Flute offers Tap to Pay on iPhone, giving businesses a powerful way to accept enterprise-level payments wherever they operate — without worrying about purchasing expensive equipment or dealing with training and maintenance. It’s the best mPOS option for small and growing teams.
If you’d like to learn about Tap to Pay on iPhone and whether it makes sense for your business, our team can help you understand your options and get started. Get in touch with us to find out more.
When a customer files a chargeback, a sale you thought was settled goes back into question. The funds come out of your account, a dispute fee gets added, and the burden of proof shifts to you. It happens more than it used to, too. Mastercard expects global chargeback volume to grow 37% by 2029, reaching 359 million disputes a year.
For a growing business, each incident costs revenue, fees, and hours of admin time.
The difference between merchants who bounce back and those who lose money to chargebacks usually comes down to having a plan. A chargeback is the start of a process with rules, deadlines, and a real chance to recover your revenue — if you know what to do.
Let’s look at what chargebacks actually are, why customers file them, and the six steps to take when one lands in your inbox.
What is a chargeback, and how does the process work?
A chargeback is a payment reversal initiated by the customer’s bank. Instead of asking you for a refund, the cardholder contacts the bank that issued their card and disputes the transaction. The bank typically gives the customer a provisional credit, pulls the funds from your account through your payment processor, and assigns the dispute a reason code that explains the claim. From there, you can accept the chargeback or challenge it with evidence.
That bank-first path is what separates a chargeback from a refund, and the difference shows up on your bottom line:
- A refund is a conversation between you and your customer: you control the timing, and your main cost is the returned sale
- A chargeback adds a dispute fee from your processor, administrative work, and a mark against your chargeback ratio, the metric card networks use to flag risky merchants
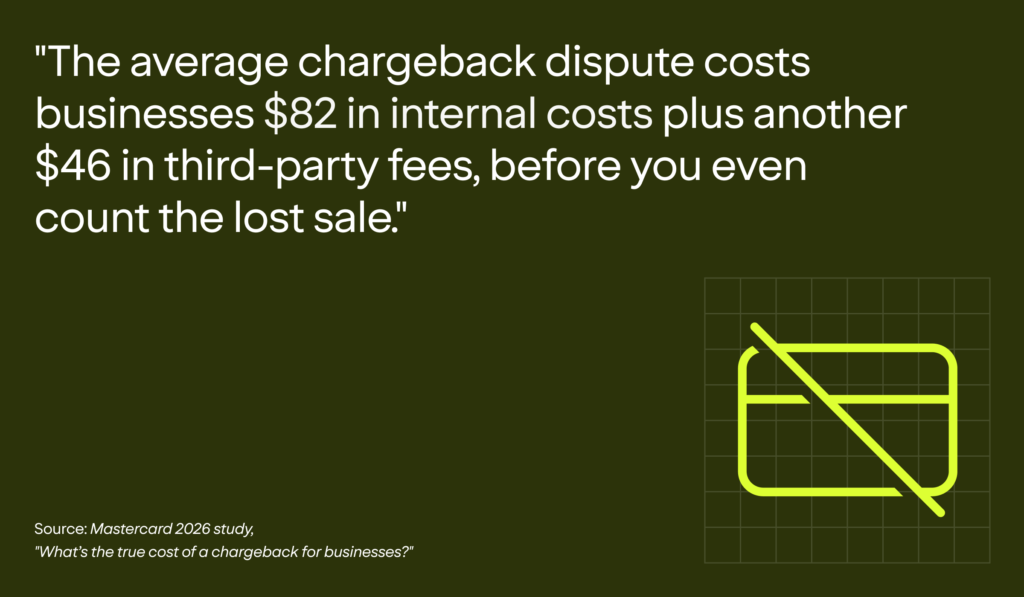
Research from Mastercard and Javelin puts the average dispute at $82 in internal costs plus another $46 in third-party fees, before you even count the lost sale.
Chargebacks exist for a good reason; they were created as a consumer protection, and they’re part of why customers feel safe paying by card at all. The trouble starts when that protection gets used in place of a simple refund request, which happens far more often than most business owners expect.
Why do chargebacks happen? The most common reasons
Nearly every chargeback falls into one of three buckets:
- True fraud: a stolen card or compromised account was used, and the real cardholder disputes the charge as soon as they spot it
- Friendly fraud: a legitimate customer disputes a charge, whether by mistake or on purpose
- Merchant error: something went wrong on the business side, like a duplicate charge, an order that never arrived, or a product that didn’t match its description
In Mastercard’s global survey research, merchants identified 45% of their chargebacks as fraudulent, a figure that includes friendly fraud alongside true fraud. However, friendly fraud is often a result of honest confusion, not bad intentions.
Mastercard found that 48% of consumers have mistakenly disputed a purchase that was actually legitimate, meaning the customer thought they had been impacted by fraud and requested a chargeback, when in reality, they just didn’t recognize the charge or remember buying anything.
Picture how easily that happens: A customer books a portrait session with a photography studio that processes payments under its parent company’s LLC. Two weeks later, a business name they’ve never heard of shows up on their statement. They don’t connect it to the photos on their wall, so they tap the dispute button. There was no bad intent anywhere in the chain, but the studio still lost the sale.
Sometimes, friendly fraud is more deliberate. A customer wants to skip the return process, regrets a purchase, or has learned that disputing feels easier than asking for a refund. Unfortunately, there’s no real way to tell what someone’s intentions are, which is why it’s so important to have documentation in case you need to dispute a chargeback.
How to respond to a chargeback: 6 steps for merchants
When a dispute arrives, the clock is already ticking. In one report, consumers said they would go straight to their bank in 75% of disputes, so the notification from your processor is often the first you hear of a problem. Unfortunately, you have a limited window to react.
Here are six steps you can take to make the most of your time and have the highest chance of winning a chargeback dispute.
1. Read the notification and find the reason code
Every chargeback carries a reason code, a short designation from the card network that tells you what the cardholder is claiming: fraud, item not received, not as described, duplicate charge, and so on. The code determines which evidence will matter, so start there. Your processor’s dashboard will list it alongside the transaction details and the amount at stake.
2. Check your response deadline
Each card network sets its own chargeback time limit for merchants. Your processor may set a shorter one, often somewhere between 20 and 45 days from the notification. Miss the window, and you lose by default, no matter how strong your case is. Find the exact date, write it down, and work backward from it.
3. Decide whether to accept or fight
Not every chargeback is worth contesting. If the customer has a point, say the order shipped late or the charge really was duplicated, accepting the dispute is the honest move and saves everyone time. If the charge is legitimate and your records can prove it, fight it.
4. Gather compelling evidence
Compelling evidence is the documentation that directly contradicts the cardholder’s claim. Imagine an online boutique owner facing an “item not received” dispute. She looks over all of her documentation and finds what she needs to dispute the issue, including the order confirmation, the carrier’s delivery scan at the customer’s address, and the thank-you email the customer sent three days after the package landed.
Depending on the reason code, strong evidence includes:
- Order confirmations, invoices, and receipts
- Tracking numbers with delivery confirmation
- Customer communication from before and after the sale
- Proof the product or service was used, like account activity
- Your refund and return policy as displayed at checkout
5. Submit a focused rebuttal letter
Your chargeback rebuttal letter, sometimes called a representment or dispute response, should be short and specific. State the reason code, summarize the transaction, then walk through each piece of evidence and what it proves. Reviewers at the bank handle a lot of disputes, and a one-page response with clearly labeled evidence will beat a pile of unorganized attachments. Submit everything through your processor before the deadline, then confirm it was received.
6. Track the outcome and learn from it
Win or lose, every chargeback tells you something. Log the reason code, the outcome, and the product or service involved. For instance, look for billing descriptors that lead to “unrecognized charge” disputes, or product pages that result in “not as described” claims. If you see the same reason again and again, that’s a good indication that something needs to change.
Keep an eye on your overall chargeback ratio as well, because card networks penalize merchants whose ratio climbs too high, regardless of who wins the individual cases.
How to prevent chargebacks in the future
The most affordable chargeback is the one that never gets filed. One study found that every $1 lost to fraud now costs about $5.13 for U.S. retail and e-commerce businesses. It’s easy for the operational, compliance, and reputational costs of managing fraud to add up, which is a strong argument for prevention over cleanup.
Here are a few best practices to follow:
- Make your billing descriptor match the business name customers know
- Send receipts and shipping notifications automatically
- Use address verification (AVS) and card security codes (CVV) for online or over-the-phone sales
- Display your refund policy clearly
- Answer customer messages fast enough that your inbox beats their bank’s dispute button
Chargeback prevention deserves a full playbook of its own, but these basics can help you meaningfully lower your dispute count in the meantime.
The bottom line on handling chargebacks
A chargeback doesn’t have to be a fire drill. Understand what the dispute claims, respect the deadline, respond with evidence that speaks directly to the reason code, and track what each case teaches you. Thankfully, the right payments partner will make every step easier.
At Flute, fraud protection and dispute support are built directly into our payments platform. That means you have access to clear dispute notifications, transaction records, and support from day one — all at no extra cost.
If disputes are eating into your margins, reach out to our team to learn how our chargeback support can help you save time and money.
Every card payment your business accepts carries a risk you can’t see. The card number is stored, transmitted, and reused, and every stop along the way is a chance for it to be stolen or misused.
In 2024, payment-related fraud cost the world $33.41 billion. Since credit and debit cards now account for more than two-thirds of consumer payments in the U.S., bad actors have more opportunities than ever to steal your customers’ payment data — especially if you’re storing their information on your own systems.
Network tokenization attacks this problem at its source. Instead of your systems handling real card numbers, transactions run on secure stand-ins that are useless to criminals and update themselves when cards change. That means you’re not only protected from fraudsters, but you also won’t have to worry about saved cards declining because they were reissued or expired.
Let’s take a closer look at what you need to know about what network tokenization, how it works, and what it does for your bottom line.
What is payment tokenization?
Payment tokenization is a security process that replaces a card’s primary account number (the 16 digits printed across the front or back) with a stand-in value called a token. The real card number is locked away in a secure vault, while the token is what travels through the payment system and is stored in databases for repeat use. If a criminal intercepts a token, they get a string of characters with no real value, effectively eliminating the potential for misuse or theft.
Tokenization vs. standard encryption
Credit card tokenization is often confused with standard encryption, but the two work differently. Here’s a quick overview:
- Encryption: Encryption scrambles card data with an algorithm, so anyone who obtains the right key can unscramble it
- Tokenization: A token has no mathematical relationship to the original number at all. There’s nothing to crack, because the token isn’t hiding the card number; it’s replacing it
Most payment systems use both. Encryption protects data while it moves, and tokenization keeps the real number out of merchant systems entirely.
The limits of traditional tokenization
Traditional tokens, sometimes called PCI tokens or gateway tokens, are issued by a payment processor or gateway. Traditional tokenization has been the standard for years, but it comes with real limitations:
- They’re static, so the same token is reused transaction after transaction
- They only work within the processor or merchant environment that created them
- They can’t always tell when a card expires or gets reissued, so when card details change, someone has to chase the customer for new numbers
The last one causes the most disruption for businesses, since every expired card means you have to deal with failed charges and awkward emails asking customers to re-enter their details.
What is network tokenization (and how is it different)?
The biggest difference between network tokenization and traditional versions is that the card networks themselves create and manage the tokens. Instead of a processor generating a stand-in number, the network behind the card, like Visa or Mastercard, provides the token and keeps it connected to the customer’s underlying account.
That connection is the superpower. Because the big card brands handle everything behind the scenes, if a customer’s card is lost, stolen, or reissued with a new expiration date, the network updates the token automatically. Payment details stay fresh without anyone lifting a finger — not you, and not your customer.
How does network tokenization work?
When a customer saves a card or makes a purchase, your payment platform requests a token from the card network. The network verifies the card with the issuing bank, creates a token tied to that specific merchant and use case, and sends it back. After that, all future transactions run on the issued token instead of the card number.
Each payment also carries a one-time cryptogram, a unique code that proves the transaction is legitimate, so even a stolen network token is useless for new purchases somewhere else.
The benefits of network tokenization
Now that you understand the basics, what does network tokenization actually do for your business? The benefits show up in four key places:
- Security
- Approvals
- Recurring revenue
- Compliance
Stronger security
Visa found that tokenization can reduce fraud by up to 60% compared to transactions that use the raw card number. The card brand also announced that tokenized payments had saved an estimated $650 million in fraud in 2023.
“[Network] tokens have changed the game — securing online payments and paving the way for more innovations — from tapping to pay on a phone to enabling a future where we have more control over our data in the age of AI,” Visa’s Chief Product Officer, Jack Forestell, said.
Because each token is locked to a specific merchant and paired with a one-time cryptogram, stolen credentials are practically impossible to decode, making this one of the safest methods of handling card payments.
Fewer declined payments
Declines are revenue killers, and many have nothing to do with a customer’s ability or willingness to pay.
For instance, with standard encryption, when a card is reissued, the cardholder has to manually update their payment information everywhere it was stored — including in their account on your website or app. If they don’t, then the next time they’re prompted to key in their payment information on your checkout screen, they might just decide it’s not worth the hassle.
Since network tokens update automatically, you never have to worry about customers abandoning their carts because their new card information didn’t carry over.
In addition, because network tokens are issued by the card brands themselves, they’re more trustworthy in the networks’ eyes. Visa’s data ties tokenization to a six-basis-point lift in global approval rates. That looks small on paper, but it’s meaningful when it’s applied to every transaction you run in a year.
Steadier recurring revenue
For subscription businesses and SaaS (software as a service) platforms, stale card data is the biggest threat to predictable revenue. PYMNTS research found that failed payments cause half of all subscription churn.
Most of those failures aren’t the customer’s fault. More often than not, customers don’t want to cancel; they just don’t remember to update their card details, so when their monthly billing cycle rolls around, you’re left with a declined payment and an uncomfortable phone call to make.
Network tokenization keeps stored credentials current across the card’s entire lifecycle, which means fewer interrupted subscriptions, fewer “please update your payment method” emails, and revenue you can actually forecast.
A lighter compliance load
Tokens hold no value outside the payment system, so businesses that store tokens instead of card numbers keep far less sensitive data on hand. That can shrink the scope of your PCI DSS compliance obligations, which lowers audit costs and limits the potential damage of a security breach.
Where payments are headed next
Network tokens power the experiences modern customers expect: tap to pay from a phone, one-click checkout, and cards saved securely across devices. Fewer forms to fill out and fewer verification hoops mean fewer abandoned carts and happier repeat buyers. Because of that, network tokenization is quickly becoming the default rail for digital commerce.
Juniper Research projects that network tokens will secure 2.4 trillion global transactions between 2026 and 2030, representing 86% of applicable transactions. Mastercard has committed to 100% e-commerce tokenization in Europe by 2030, phasing out manual card entry altogether.
The card networks are treating tokens as the foundation for whatever comes next, from Click to Pay to AI-assisted purchases. For merchants, the question is shifting from “should we tokenize?” to “why haven’t we yet?”
Getting started with network tokenization
Adopting network tokenization starts with your payment platform. The right one will handle network token provisioning, lifecycle updates, and cryptogram management behind the scenes, so you get the security and approval benefits without development work, hardware changes, or downtime.
At Flute, network tokenization is integrated into our payments platform from day one, alongside the secure customer vault, recurring billing, and reporting tools growing businesses rely on.
Reach out to our team to get started and see what network tokenization can do for your bottom line.
Last year, agentic commerce hit the market, and the headlines said we would never shop the same way again. In reality, the new technology hasn’t taken off like it was expected to.
Here’s what actually happened: OpenAI launched Instant Checkout in September 2025, and Walmart and Target signed on within weeks. By March 2026, OpenAI had quietly pulled the feature back. Walmart reported that in-chat purchases converted at about one-third the rate of those that required clicking out to its own site.
If the biggest names in retail hit pause on AI shopping, what does that mean for a growing business that’s been wondering whether to care at all?
Let’s break down what agentic commerce is, why it hasn’t seen mainstream adoption, and why small- and medium-sized businesses should care about the future of this new payment technology.
What is agentic commerce?
Agentic commerce is an emerging technology that allows AI agents to shop and buy things for you. Instead of browsing sites, comparing prices, and typing in card numbers yourself, you tell an AI agent what you need, and it handles some (or all) of the process on your behalf.
That “some or all” distinction matters more than it might sound. It all comes down to how advanced the AI agent is and how much you trust it.
The two sides of agentic commerce
There are two distinct halves to agentic commerce, and they’re progressing at very different speeds.
The first is discovery, which covers everything that happens before a customer decides what to buy. This is where consumers rely on AI agents to compare products, read reviews, check prices across sites, and recommend an option based on what it knows about the shopper. Because the AI agent doesn’t make any final purchases during discovery, this phase has seen much wider adoption.
The second half of agentic commerce is the transaction itself. Here, the agent provides payment details and completes the purchase on the customer’s behalf. This is where adoption dramatically slows. Shoppers are comfortable letting an AI shopping assistant do product research, but far fewer will let one spend their money — especially without any oversight.
Why has agentic commerce stalled?
Ask yourself this: would you trust a chatbot to spend $300 for you, or would you rather review its suggestion and then enter the card number and confirm the final purchase yourself?
Accenture’s 2026 Consumer Pulse research found that only 9% of respondents would let an agent complete a purchase autonomously. Forrester agrees, calling consumer adoption of AI-driven checkout “lukewarm.” AI agents make mistakes, and until this technology becomes more reliable, shoppers will continue to feel hesitant about trusting agents with their money.
Structural challenges are also contributing to consumer hesitation. Competing protocols are still being fleshed out, and the industry hasn’t agreed on how to verify an AI agent’s identity or catch fraud before it happens.
Despite the limitations, the industry is moving in the right direction. For instance, Google launched its Universal Commerce Protocol in January 2026 with major retailers on board and public backing from Mastercard and Visa. It’s a sign of where things are heading, even if adoption is still early.
That said, Juniper Research has projected that agentic commerce transactions will grow in value from $8 billion today to $3.5 trillion by 2031. But that growth will depend on consumer trust, better fraud tools, and clearer rules around who’s responsible when something goes wrong.
What merchants should do now
Visibility matters more than checkout right now. The discovery half of agentic commerce is already live, so the real opportunity is being found and recommended by agents. While it might still seem futuristic, it’s important to invest in discovery now. If AI agents don’t know anything about your business, then when the time comes for them to start purchasing on your customers’ behalf, there’s a good chance they’ll buy from your competitors instead.
Here are a few steps you can take today to make sure your business starts showing up in the discovery phase:
- Structure your product data: Most pages cited by AI shopping tools contain structured data, so whether an agent can find and recommend a business comes down to having detailed titles, complete product attributes, and a clean catalog on your site
- Keep descriptions accurate and current: Update product descriptions wherever they live so they stay detailed and correct. That investment will pay off in today’s search results and in future agentic scenarios
- Nail the fundamentals: Answer engine optimization (AEO) builds on the same groundwork as search engine optimization (SEO), which means you need the same basics to be found by AI as you would to be found on Google. That includes having accurate inventory, clear pricing, real customer reviews, and a clean, fast website. Thankfully, none of that work will go to waste, no matter how the checkout side shakes out
- Hold off on overhauling anything: The protocols haven’t settled, and the companies that rushed in first are the ones paying the first-mover tax. While it’s important to set yourself up for success from a discovery standpoint, take a step back and watch where the industry is heading before you make any big tech investments for the purchasing side of the journey
Agentic commerce now and in the future
Agentic commerce isn’t a failure. The transaction piece just proved harder than the hype suggested. The businesses that come out ahead will be the ones that make themselves visible while agents learn to shop. If you take the right steps today, you’ll be ready for the moment AI agents start making real purchases for your customers.
Flute keeps an eye on agentic commerce so growing businesses can stay focused on running theirs. Reach out to our team to see how we’re keeping payments simple, even while the industry changes.
ACH is the system behind many bank-to-bank transfers in the United States. It powers direct payroll deposits, most recurring bank payments, and a fast-growing share of business-to-business invoices. In each case, money moves directly from one bank account to another, with no card or paper check in between.
How you get paid shapes your margins, your cash flow, and how often invoices arrive on time. For growing businesses, ACH payments offer a way to cut card processing fees and streamline how you collect and send money.
To help you better understand this payment type, let’s take a closer look at what ACH payments are, how the process works, and when a bank transfer is the smarter way to accept and send payments.
What are ACH payments?
ACH stands for Automated Clearing House, an electronic network that moves money from one U.S. bank account to another. That system carries an astonishing amount of money. In 2024, the ACH Network moved 33.6 billion payments worth $86.2 trillion.
When you hear someone mention an ACH payment, a bank transfer, or an eCheck, they’re usually pointing at the same thing: funds moving directly between accounts, with no card network, paper check, or cash changing hands.
The network is governed by Nacha, the organization that writes and enforces the rules every participating bank and payment provider has to follow. That oversight is one of the reasons ACH is both dependable and affordable — it follows strict compliance regulations and cuts out middlemen like the big card brands.
Because the ACH network was built specifically for payments inside the United States, it’s a poor fit for most international transfers.
How the ACH payment process works
Behind every bank transfer is a straightforward exchange between two accounts. The ACH payment process generally follows four steps:
- A request begins: You or your payment provider starts a transfer, either to pull money from a customer’s account or push it into one
- The payment joins a batch: Rather than moving one at a time, transactions are grouped together and sent to an ACH operator
- The operator sorts and routes: Each payment is directed to the correct receiving bank
- The funds settle: Both banks confirm the details and update the accounts
An ACH credit pushes funds into an account, the way a direct deposit delivers payroll or a business pays a supplier. An ACH debit pulls funds from an account with the account holder’s permission, which is how most companies collect invoices, dues, and recurring bills.
Most transfers finish within one to two business days. When timing matters, Same Day ACH can settle eligible payments within hours. Businesses are leaning on this payment method more every year. In 2024, Same Day ACH volume climbed 45.3% to more than 1.2 billion payments.
When ACH payments make the most sense
ACH isn’t the right fit for every sale. When a customer is grabbing a coffee or checking out at the counter, tapping a card is hard to beat. But in a handful of situations, a bank transfer wins on cost, reliability, or both.
Recurring and subscription billing
If your revenue depends on recurring payments, like memberships, retainers, rent, or software subscriptions, ACH debits are the right approach. Once a customer authorizes the transfer, each payment runs on a set schedule without anyone having to re-enter their payment details.
This helps businesses reduce costs by sidestepping the typical fees associated with credit card processing. It also ensures payments keep flowing even when a card is reissued or replaced.
That kind of reliability keeps getting more valuable. Juniper Research projects the subscription economy will nearly double to $1.2 trillion by 2030. For any business that bills on a cycle, a payment method that keeps working in the background is what separates steady revenue from a monthly scramble.
Large B2B and B2G payments
You’ve just delivered a $40,000 wholesale order to a restaurant group you’ve supplied for years. The owner asks how she should pay. You have two options: mail an invoice and wait a week or more for a paper check that might get lost or sit in a drawer — or collect the payment by bank transfer and watch it land in your account, with none of that $40,000 shaved off by card fees.
In 2024, B2B ACH payments grew 11.6% to 7.3 billion. ACH payments are more reliable than wire transfers or checks, making them the best payment option for large, business-to-business transactions.
As Nacha’s President and CEO points out, “The growth in B2B that began accelerating during the pandemic shows no signs of abating. Checks continue to lose favor, given the many problems they present, particularly safety issues.”
Government payments are heading in the same direction. In 2025, the federal government stopped issuing most paper checks, shifting tax refunds, benefits, and vendor payments to electronic methods like direct deposit. If you sell to public agencies or large institutions, being ready to send and receive ACH is fast becoming the price of entry.
Low-cost and zero-cost processing
Card processing usually takes a percentage of every sale, typically 2% to 3.5%. On a large ticket or a recurring charge, that adds up quickly. ACH changes the math with a small, flat fee. One recent survey found that initiating and receiving an ACH payment costs a median of $0.26 to $0.50, while issuing a single paper check costs $2 to $4.
Those low, predictable costs are also why ACH fits naturally into low-cost and zero-cost processing strategies. For high-value invoices or anything billed on repeat, shifting even part of your payment volume to ACH can help you reduce operating costs without raising your rates.
Are ACH payments safe?
For most businesses, ACH is as safe as, if not safer than, other payment methods. Every transfer runs through a regulated network with bank-level encryption, account verification, and a digital record of each transaction, making reconciliation and dispute resolution simpler than keeping track of a paper trail.
Bank-to-bank payments are especially more secure than traditional paper checks. A fraud survey released in 2025 found that checks were the payment method most often targeted by fraud, hitting 63% of organizations. Mailed checks put your account and routing numbers in front of everyone who handles them, while ACH transfers keep those details inside a secure system.
Should your business accept ACH payments?
There are several reasons to consider ACH payments — especially if your business takes recurring payments or deals with large business-to-business or business-to-government transactions.
Here are a few advantages:
- Lower, more predictable fees than credit cards
- Reliable recurring billing that keeps income flowing
- Faster settlement, with same-day options when you need them
- Fewer late payments, thanks to automated collection
- A secure, fully digital record behind every transaction
ACH won’t replace cards at the register, and it isn’t meant to. But for your largest, most regular, and most cost-sensitive payments, a bank transfer is tough to beat.
That’s where Flute comes in. We make it easy for growing businesses to accept ACH alongside cards, automate recurring billing and invoices, and get paid faster, so more of what you earn stays in your business. Reach out to our team to get started.
Getting paid should be the easy part of running your business, but for operators that bill the same customers on repeat, it often isn’t. Someone still has to figure out the charges, send out invoices, follow up on declined cards, and track down the member whose card expired last quarter. If you offer subscription plans, memberships, or any other program that relies on regular, repeat transactions, manually collecting payments burns a lot of time — time that would be better spent on more important tasks. It can also leave you guessing from one month to the next.
That uncertainty can carry a lot of weight. In the Federal Reserve’s 2024 Small Business Credit Survey, more than half of firms (51%) named uneven cash flow as an ongoing challenge. When you can’t count on money landing when you expect it, everything else gets harder to plan.
Recurring payments offer a way out of the cycle. These are automatic payments that run on a schedule you set, charging a customer’s saved card or bank account without anyone having to ask. Instead of sending an invoice and hoping it’ll get paid, these tools make it possible to collect payments on time, automatically.
Let’s look at what recurring payments are, how they work behind the scenes, which industries get the most out of them, and how to start using these tools yourself.
What are recurring payments?
A recurring payment is a charge that repeats automatically on a schedule, using payment information your customer has authorized you to keep on file. You might know the idea by other names — automatic payments, subscription billing, or recurring billing — but the mechanics are the same. The customer signs off once, and the charges continue until someone cancels.
This covers far more than streaming services. Gym memberships, monthly retainers, maintenance plans, software subscriptions, and installment plans all run on recurring payments. The model fits almost any business that delivers something regularly and would rather collect on time than ask for payment after the fact.
How do recurring payments work?
At the simplest level, a recurring payment starts with permission. Your customer agrees to the amount and the schedule, then enters their card or bank details. From there, your recurring payment processing system charges them automatically each cycle and sends a receipt. No one re-enters a card number. No one mails a check.
However, what happens to those payment details next matters more than most business operators realize.
How is payment data protected?
Sensitive information, like a customer’s payment details and personal information, can quickly become a target for fraud and a compliance burden. That’s why you never want a customer’s card number living on your own systems. Instead, it’s important to find a payment provider to store everything on your behalf.
Most will keep that information in a customer vault — a secure, encrypted environment that never touches your own systems. The vault works hand in hand with network tokenization, which swaps the real card number for a token: a stand-in that’s useless to anyone who manages to intercept it. When your provider handles everything on your behalf, the security and compliance headaches of storing card data never land on you.
The same setup also keeps payments from breaking. When a customer’s card expires or is reissued, the token updates behind the scenes, so the next charge goes through without a missed payment or having to ask them to re-enter their card details.
How recurring payments help your business grow
This is where recurring payments earn their keep. Once you have everything set up, you’ll start to see a few meaningful benefits:
- Predictable timing: payments run on a schedule you choose, whether that’s weekly, monthly, or quarterly, so you always know when the next payment is coming
- Reliable income: customers continue paying until they decide to cancel, which gives you revenue you can actually plan around
- Less busywork: there are no invoices to send, due dates to track, or late payments to call about
- Fewer failed charges: with network tokenization, cards update automatically when they expire or get reissued, so you never have to worry about unexpected setbacks
- Lower processing costs: long-term customers often prefer ACH bank payments (direct bank transfers) over cards, which can cut credit card fees considerably
- Stronger security: encryption and tokenization backed by the major card brands protect every charge, and letting your provider handle sensitive data lowers your compliance burden
Predictable, automatic payment flows do more than save time; they create room to grow. In one study, 88% of firms using faster payment options like recurring billing reported business growth. With the right provider, you can streamline repeat purchases or membership billing without the headache of handling collections yourself.
What industries benefit most from recurring billing?
The subscription model is expanding fast. Juniper Research projects the global subscription economy will grow 67% to $1.2 trillion by 2030. You don’t have to sell streaming or software to tap into that growth — any business with repeat customers and steady service can put recurring billing to work.
Here are a few industries that benefit most:
- Fitness and wellness: gyms, yoga studios, and martial arts schools with monthly memberships
- Salons and spas: membership packages for regular cuts, facials, or standing massage appointments
- Professional services: bookkeepers, agencies, and consultants working on monthly retainers
- Home and field services: pest control, lawn care, pool maintenance, and seasonal HVAC tune-up plans
- Health and dental practices: in-house membership plans, orthodontics, and ongoing therapy
- Education and lessons: tutoring centers, music teachers, and online course access
- Pet care: grooming plans, dog walking, and veterinary wellness memberships
These are just a few of the most common industries using these tools. If you need the ability to accept payments on a regular basis without having to manage everything yourself, recurring payments are worth looking into.
Getting started
Recurring payments take the monthly chase off your plate. You set the schedule, charges go through on time, and a secure vault keeps cards current and customer data protected.
Getting started is easier than you’d expect. The right software will offer scheduling, have a built-in customer vault, and handle network tokenization behind the scenes, so you can collect automatically without taking on the hassle of doing it all yourself. Simple, streamlined payments on a predictable schedule — that’s exactly what our recurring billing tools were built for.
If you’re ready to learn more, reach out to our team to see how recurring payments can make repeat purchases, subscriptions, and memberships a reliable source of income for your business.